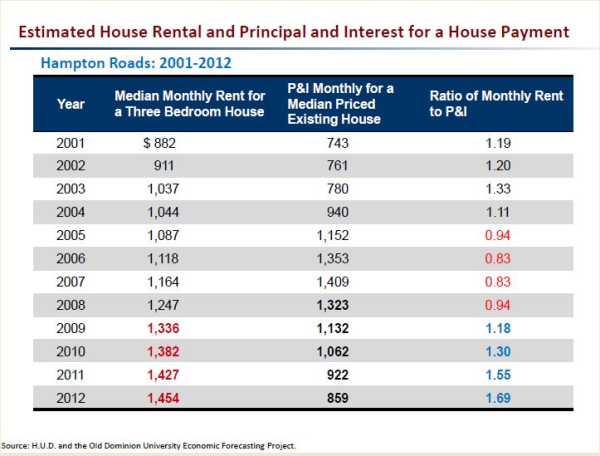
You’ve just been relocated to Hampton Roads, and you need a place to live …should you find a place to rent, or should you look for a home to buy? You should never underestimate the simple emotional considerations of home ownership; however, there are number of investment factors that you should also evaluate before making a commitment:
What are the circumstances surrounding your housing decision? For instance, how long will you be in the area? What are your goals?
Begin with the qualification process. How much mortgage can you afford? How large a monthly payment are you comfortable with? As a general guideline, lenders like to see your house payment not exceed 28% of your adjusted gross income, and your entire monthly debt not exceed 41%. There are many exceptions to this rule, and many extenuating factors that may result in higher %’s, but it’s a good place to start. Next, look at what that amount will buy, both in the housing and the rental market. The first step in the evaluation is comparing apples to apples. What is available? What is the inventory supply of choices, both in the housing market and in the rental market?
Assuming that you select a fixed rate mortgage, your house payment will remain the same over the term of your loan, versus a rent payment that will adjust annually to meet inflation. During the first years of the comparison, your out of pocket expense is likely to favor renting; quite simply that cost (rent vs. your house payment including taxes) from a cash flow standpoint will probably be less to rent. This is where it is important that you dig a little deeper, to consider the big picture of that comparison.
Let’s compare a $300,000 purchase with a comparable rental. Assuming a 20% down
payment, and a 6.5% 30 year fixed mortgage, your house payment would be $1,580, plus another 20% roughly for taxes and insurance, for a total payment of around $1,900. Let’s assume a comparable rental will be $1,400 per month. On the surface, that seems to be a $500 savings per month, or a $6,000 annual benefit to renting.
The first adjustment you’ll need to make is to factor in the tax benefits of home ownership. On a $250,000 loan at 6.5% interest for 30 years, for instance, your interest deduction in the first year would be $16,167. So, if you are in a 25% tax bracket, that deduction will save you $4,041 in taxes, or $337 per month. That means that your “effective” mortgage payment after the tax benefit is $1,563.
Because of inflation, your rent will escalate annually based on the terms you’ve negotiated in your lease. Commonly, escalation clauses fall somewhere between 3 and 4% per year. So, the $1,400 rent payment this year will become $1,622 in 5 years based on a 3% escalation…whereas your mortgage payment remains fixed at $1,900.
Over time, more and more of your mortgage payment will be applied to reducing the principal balance of your loan, which is in and of itself a forced savings program.
Most importantly, and generally considered the most important advantage of home ownership, is the inherent value of appreciation. It’s pretty safe to use a factor of 4-6% appreciation over time. So, as an example, a $300,000 purchase increases in value to $382,884 in just 5 years (based on a conservative appreciation factor of 5%), because as a homeowner, you enjoy the appreciation based on your sales price, not just your investment.
Let’s assume that you chose to rent, and so you invested the $50,000 that you saved because you didn’t make a down payment in the stock market. Using the same 5% rate of return, your investment grew from $50,000 to $63,800 over those same 5 years, netting you almost $14,000, compared to the $83,000 in equity you built during the same period as a homeowner (and that does not factor in principal reduction).
The other important consideration here is that in order to even net $14,000, you have to invest the money you didn’t use as a down payment. Most renters are not that disciplined, which is another argument for why homeownership is a great “forced” savings plan.
There is one potential downside to the rent vs. buy analysis, and that is market timing. If you’re not in a position to hold your investment long enough to enjoy the benefits of appreciation and equity growth, or worse, if you are forced to liquidate at a down cycle in the market, the equation may not be as favorable.
In order to avoid that, one recommendation is to considering holding on to a property as a rental investment, rather than selling at a low point in the market. Although you may face the consequence of negative cash flow in order to do that, the promise of equity gain over the longer cycle may outweigh the short term discomfort.
Let’s recap. When you consider the price of inflation and the tax benefits of mortgage interest deductions, for the most part, the cash flow comparison of renting vs. buying is a close call ~ the out of pocket cost is close to the same.
When you add the investment value over time of (1) principal reduction, and (2) appreciation on the leveraged sales price vs. the amount of your investment, the answer is pretty clear. There is a reason that for many years, the American Dream of home ownership is also the most effective way for most individuals to build wealth over time.
To determine what the best decesion is going to be for you, start with getting pre-qualified. This should be done before you begin to house hunt, to answer your questions and help you determine an initial price range within your comfort zone.
It's Free, Easy, and with No Obligation!

Stay up to date
Browse Posts
- October 2026
- September 2026
- July 2026
- June 2026
- May 2026
- April 2026
- February 2026
- January 2026
- July 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
Browse by topics
- Buyers (14)
- Locals - 101 Reasons (0)
- Sellers (7)
- Williamsburg (1)
- New Homes (0)
- Home Sale Statistics & Trends (6)
- Community (47)
- event (0)
- Newport News (0)
- lizlocal-richmond-realestate (48)
- lizlocal-williamsburg-realestate (49)
- lizlocal-peninsula-realestate (44)
- York County (0)
- events (0)
- Richmond (0)
- lizlocal-NorthernNeck-realestate (42)
- Fords Colony (0)
- Home Page (0)
- event-Peninsula (0)
- Hampton (0)
- Neighborhood Spotlight (4)
- lizlocal (0)
- event-Williamsburg (1)
- event-Richmond (0)
- Poquoson (0)
- Seniors (8)
- lizlocal-richmond-community (21)
- lizlocal-williamsburg-community (22)
- About (27)
- lizlocal-Peninsula (0)
- careers (1)
- lizlocal-Richmond (0)
- Investors (0)
- lizlocal-Peninsula-community (18)
- lizlocal-Williamsburg (0)
- lizlocal-NorthernNeck-livelocal (13)
- relo-richmond-local (0)
- relo-williamsburg-local (0)
- relo-peninsula-local (0)
- Military (0)
- lizlocal-NorthernNeck-community (15)
- lizlocal-peninsula-livelocal (11)
- lizlocal-richmond-livelocal (12)
- timeline (0)
- MarketTalk (18)
- lizlocal-williamsburg-livelocal (12)
- Rivers Bend at Uncles Neck (0)
- Peninsula (2)
- Monticello Woods (0)
- 55+ (9)
- Downsizing (9)
- New Kent (0)
- Perkinson Homes (0)
- buyer (4)
- Oaks at Fenton Mill (0)
- WYD1 (8)
- commercial (8)
- lizlocal-NorthernNeck-food_and_drink (5)
- RVA Home Building (0)
- WYD3 (7)
- buy (7)
- lizlocal-richmond-food_and_drink (4)
- relo-richmond-news (0)
- WYD4 (6)
- WYD5 (6)
- golf (0)
- relo-peninsula-news (0)
- relo-williamsburg-news (0)
- Brickshire (0)
- Kingsmill (0)
- Quarterpath (0)
- WYD2 (4)
- Westport (0)
- land (0)
- Braemar Creek (0)
- Chesterfield (0)
- Hilton Village (0)
- Kiln Creek (0)
- New Town (0)
- Patriots Landing (0)
- Queens Lake (0)
- Village Park (0)
- lizlocal-peninsula-food_and_drink (1)
- lizlocal-williamsburg-food_and_drink (0)
- waterfront (0)
- 101 (0)
- Colonial Heritage (0)
- Coventry (0)
- Governors Land (0)
- Greensprings West (0)
- Port Warwick (0)
- Smithfield (0)
- Stonehouse (0)
- Virginia Beach (2)
- White Hall (0)
- seller (1)
- Brandermill (0)
- Brandon Woods (0)
- Data Centers (1)
- Greater Richmond (1)
- Hallsley (0)
- Hampton Park (0)
- Hampton Roads (1)
- Hanover (0)
- Home Values (1)
- Homeowners (1)
- Merrimac Shores (0)
- Midlothian (0)
- Norfolk (1)
- Real Estate Trends (1)
- Running Man (0)
- The Greenlands (0)
- The Settlement At Powhata (0)
- Villas at Oxford Run (0)
- West Point (1)
- Woodlake (0)
- kensington Woods (0)
- lizlocal-richmond-liz_local (1)
- lizlocal-southside-livelocal (1)
- press release (1)
- the point on fishers creek (0)
Liz Moore & Associates is a boutique real estate agency renowned for having the region's top agents, with extensive market knowledge and local expertise that is only achieved through relentless training coupled with Liz's extremely high standards for professionalism. When you're buying or selling a home, experience matters.